

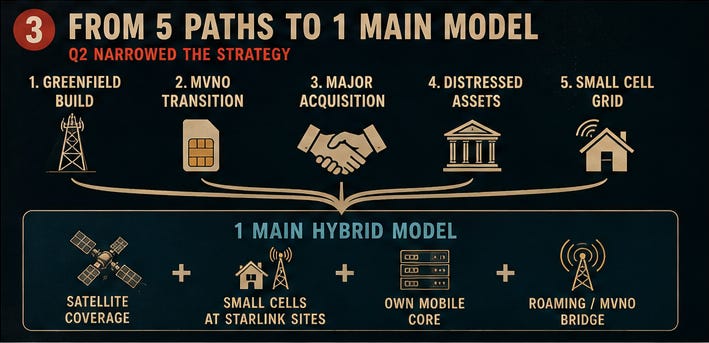
A few weeks ago, I mapped five ways SpaceX could enter the U.S. mobile market. A greenfield build, an MVNO agreement, a major carrier acquisition, distressed asset purchases, and a decentralized small cell grid. At that point, Musk clearly wanted the market. The operating model was still open.
The second quarter financial results closed most of that. SpaceX did not formally rule anything out, but the first set of public accounts tells you where the capital goes, and capital allocation is a more honest statement of intent than anything said on a call.
The answer is one architecture plus one bridge. An inside-out network built on satellites, owned spectrum, a SpaceX core, and distributed small cells at customer premises, with wholesale terrestrial access underneath it wherever the satellite and the cells cannot reach. That much is roughly what I expected.
What I did not expect is what the quarter says about priority. This is not a man building a telco; it is a company using a telco to build something else.
The capex boom said a lot
SpaceX reported second-quarter revenue of $7.81 billion, up 92% year over year, with adjusted EBITDA of $3.5 billion and a net loss of $541 million, narrowed from $1.0 billion a year earlier. Operating loss was $143 million. Most Analysts were expecting $6.8 billion of revenue and a $1.9 billion loss.
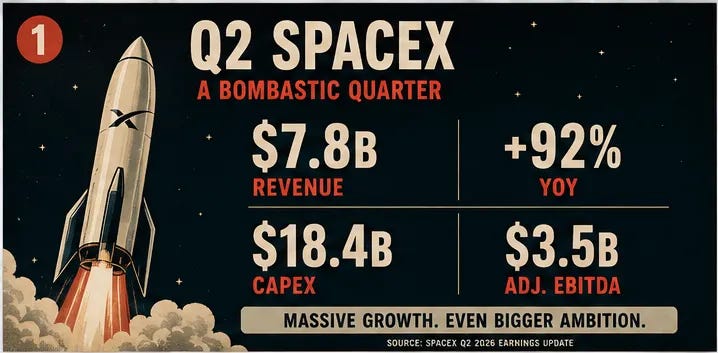
That is a strong first public quarter. The stock fell as much as 8% after hours anyway, and the reason was the brutal investment to keep the space machinery moving. Capital expenditure was $18.37 billion against an analyst estimate near $13 billion. Of that, $15.83 billion was AI capex.
Please read that again in the context of a telecom argument. 86% of the quarter’s capital went into compute. Connectivity and Space divided the remaining $2.5 billion between them.
Now, lets´s put the growth rates around it. Connectivity revenue was $4.29 billion, up 66%. AI revenue was $2.56 billion, up 247% year over year and 213% sequentially, with segment adjusted EBITDA turning positive at $1.15 billion despite a $1.26 billion operating loss. The company also agreed to acquire the AI coding firm Cursor for $60 billion, expected to close in the third quarter.
So inside SpaceX, every dollar spent on a terrestrial radio competes with a dollar spent on GPUs, and the GPU business is growing roughly four times faster. Anyone modeling a rapid nationwide small cell rollout has to explain why that capital wins an internal argument it is currently losing by a factor of six to one.
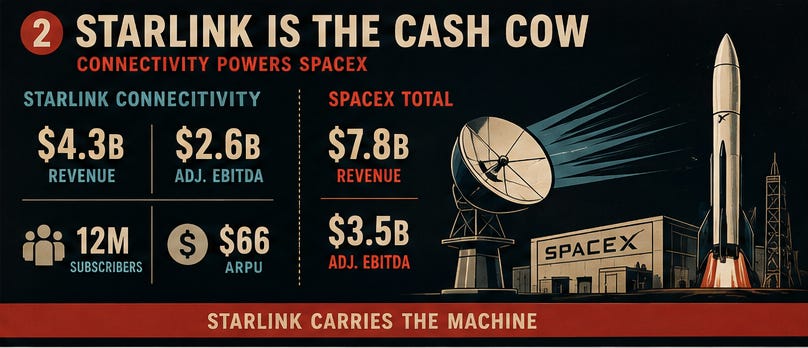
This is the part of the story the industry has not absorbed yet. Connectivity is not the destination; instead, it is the cash engine and the distribution channel. Starlink throws off money; the money goes into compute, and the customer relationship matters because it is the last mile for whatever eventually gets sold across it.
Which changes the shape of the threat. Nobody is trying to become the fourth U.S. carrier. Musk is trying to make the carrier a component.
The architecture, and the dependency
On the Q2 call, Gwynne Shotwell said SpaceX intends to build the terrestrial component of Starlink Mobile, including the hardware and systems a real mobile service requires, and discussed placing a cellular base station on the equipment supporting a Starlink dish. Musk argued that large numbers of small stations on homes and businesses could reduce dependence on expensive macro sites.