

Ericsson and Nokia are not growth experiments. They are 150-year industrial survivors, built in Nordic economies where capital is scarce, winters are long, and demand cycles are unforgiving. Both companies endured wars, currency resets, technological ruptures, and repeated telecom capital expenditure collapses. Their operating DNA prioritizes balance sheet strength, cost discipline, and endurance over narrative. When markets flatten, their financials become a proxy for the health of the entire telecom equipment industry.
That makes the 2025 full-year results quite revealing. Global RAN spending remained flat, operator capex stayed constrained, and pricing pressure intensified. Ericsson exited 2025 with roughly $22 billion in revenue, an operating margin of around 17 percent, $5.8 billion in net cash, and announced $2.3 billion in shareholder distributions. Nokia closed the year with roughly $26 billion in revenue, an operating margin of around 9% reported and 17% on a comparable basis, and $3.7 billion in net cash, supported by Network Infrastructure demand.
Although both companies broadly met financial expectations, market reactions diverged sharply, particularly with respect to confidence in the durability of their forward earnings.
That divergence helps us understand the state of telecommunications in 2026.
Ericsson 2025: Solid performance but weak growth story
Ericsson ended 2025 with revenue of roughly $22.0bn, delivering 2% organic growth in a year where management, analysts, and peers all describe the global RAN market as flat. Beyond those numbers, there is an interesting focus on financial discipline.
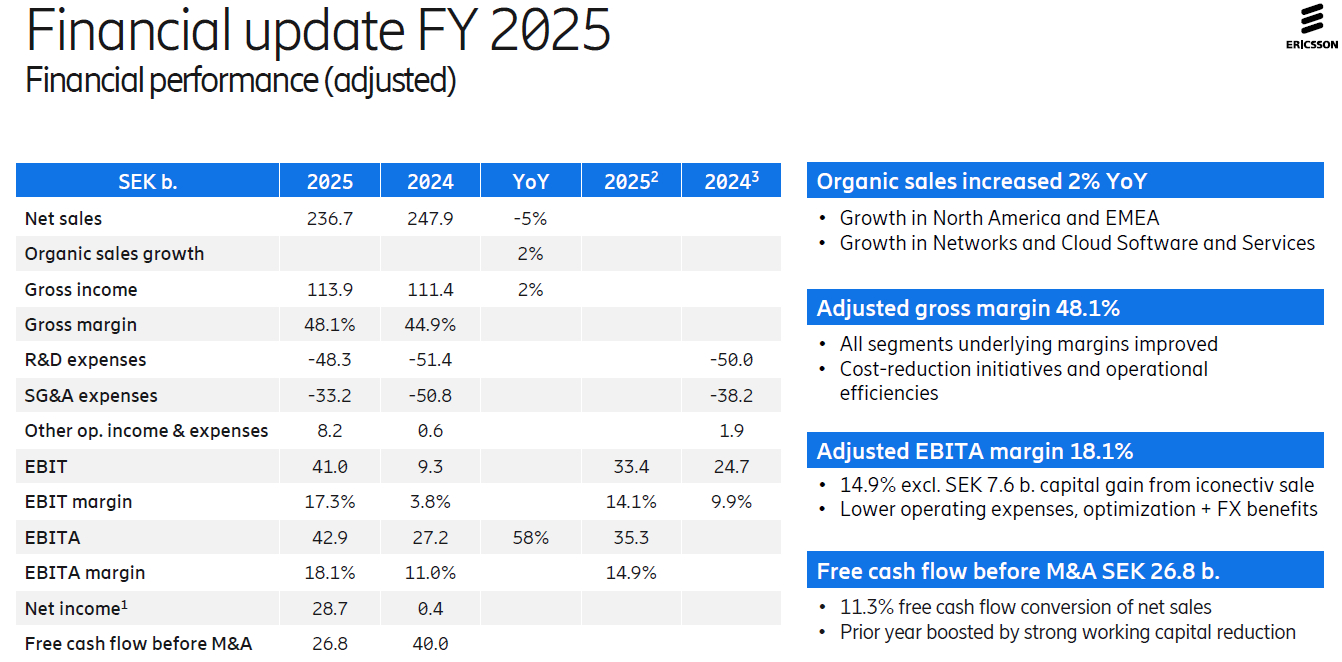
Ericsson reported an operating margin of 17% and an EBITDA margin of 18%, while gross margin stabilized at 48%, a step change from the mid-40s profile of the previous cycle. Free cash flow before M&A reached $2.5bn, equal to 11% of revenue, and net cash closed the year at $5.8bn.